The Leading News & Information Service For The Facilities, Workplace & Built Environment Community
Are Heat Pumps Really The Future? The Balance Between Policy & Reality
Rinnai Director Chris Goggin confronts the question surrounding heat pump installations: how does the idea of heat pumps being classified as the primary solution towards domestic and commercial decarbonisation compare to the direction of the UK low carbon heating and hot water technology market?
For policy updates and latest information on Rinnai products and projects subscribe to our free newsletter:
Heat pumps are a huge part of the UK's plans to lower carbon emissions, but to fulfil the aims of the UK Department of Energy Security and NetZero, heat pumps must become more accessible and widespread throughout UK properties. As the UK is slower in its uptake of heat pump technology when compared to European nations, how does centralised insistence of heat pump ownership correlate to the reality of the low carbon heating and hot water market?
Heat pumps are a viable technology that efficiently provides warmth and heated water. Although the UK is still reliant on fossil fuels, heat pump adoption is a growing trend amongst UK customers. Currently just 1% of UK homes use heat pumps as a primary source of heating and hot water. For every heat pump sold there are 15 gas boilers purchased.
But, as of 2024 UK heat pump sales were recorded at 98,345, up from 62,906 from 2023. Between 2025 and 2030 the UK heat pump market is expected to expand by 11.10% CAGR (Compound Annual Growth Rate). Heat pump awareness and popularity is evidently rising.
The UK government has outlined a pathway to decarbonisation that aims to reach 600,000 heat pump installations per year by 2028.
Considering that heat pump proposals were set from October 2020 via the UK government's Ten-Point Plan, the UK is still not even halfway towards achieving their 2028 target.
Reading these figures does force the question: is there a balance between heat pump policy and the reality of the UK low carbon technology market?
The reality is that heat pump installations are rising year upon year, yet significant barriers remain. Gas boilers typically have lower upfront costs, whilst the running costs of heat pumps can vary depending on electricity prices, system design, building fabric and tariff selection. For commercial buildings, additional challenges such as electrical infrastructure upgrades, plant room constraints and capital investment requirements can influence technology decisions.
Despite these challenges, the direction of travel remains clear and recent policy changes are helping to close the gap between government ambition and market reality.
However, there have been several noteworthy recent adaptations to policy that attempts to reduce costs and increase accessibility to heat pumps, closing the gap between UK policy and the current low carbon heating and hot water market reality.
UK (England) heat pump regulations have been amended to accommodate property owners. A size limit has been increased from (0.6m^ {3} ) to (1.5m^ {3} ). This regulatory adaptation allows for higher efficiency systems to be installed.
A further regulation that has been adjusted is the removal of the Boundary Rule. This rule demanded that heat pump installations be 1 metre away from the boundary of the property.
Detached homes can now install up to 2 heat pumps without the need for planning permission from the LPA (Local Planning Authority).
Noise compliance is an area of heat pump ownership that has been regulated to ensure communities will not suffer from excess decibels. Heat pump installations must pass a formal sound power test. Typical limits require noise levels to remain at or below 42 dB or 40 dB during the evening and night (19:00 to 07:00) at the property boundary.
Domestic heat pumps will now have to be “Smart-ready,” meaning that heat pumps will be able to select the cheapest energy tariff at any given moment based on demand.
A final regulatory shift centres on cooling systems; air-to-air heat pumps that offer both heating and cooling are now included under permitted development, on the provision that cooling is not the sole purpose.
These are the domestic updates in regard to heat pump installations. What are the commercial regulatory changes that business owners should be aware of?
Any new commercial new-build property must be required to include ultra-efficient, low-carbon heating systems like heat pumps as opposed to fossil fuel systems. This directive is published in the Future Building Standard.
Modern commercial heating design increasingly favours lower flow temperatures, often around 55°C or below where practical, as this can improve overall system efficiency and support the adoption of low carbon technologies such as heat pumps.
The “Clean Heat Market Mechanism” is a financial obligation placed on fossil fuel boiler manufacturers and can be viewed as gas boiler taxation. If a manufacturer does not reach a low-carbon heat target of 8% then financial penalties will be imposed. This decision is expected to increase heat pump deployment and further stimulate the low carbon heating market. Whilst supporters believe it could help reduce costs through increased adoption and manufacturing scale; there remains ongoing debate regarding how costs and savings will ultimately be passed on to consumers.
F-Gas regulations have been updated phasing out commercial heat pumps that include harmful refrigerants during operation. Heat pump designers will now have to utilise eco-friendly refrigerants such as R290 and R32.
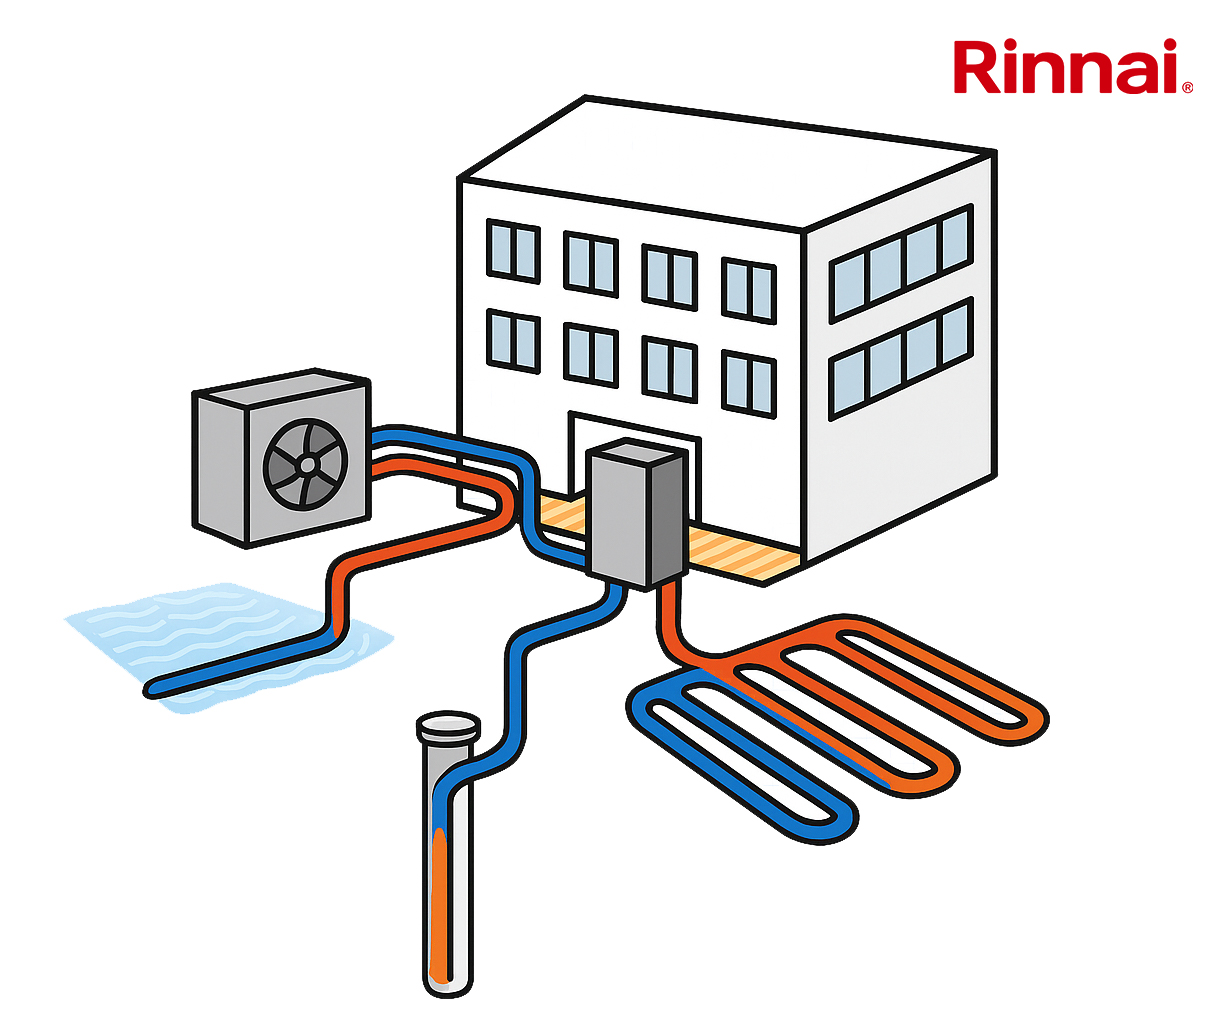
Non-domestic and community buildings have been awarded beneficial permitting development rights. It is now easier to install ground or water source heat pumps without confirming full local authority approval. However, air source heat pumps are still under local power authorisation and must comply with noise lowering standards.
However, significant practical challenges still exist, particularly within the commercial sector. Electrical infrastructure remains one of the largest barriers to large-scale heat pump deployment. Many existing buildings were not designed for high levels of electrification and upgrading incoming electrical supplies can involve substantial costs, lengthy lead times and coordination with Distribution Network Operators. These factors must be carefully considered alongside policy ambitions.
New regulations also ensure that new-build properties must now be equipped with high efficiency and low carbon heating systems and fossil fuel boiler manufacturers are now motivated to include heat pump in their inventories or face financial penalties. This is theorised to assist in the initial cost of investing in a heat pump more bearable.
Whilst heat pumps will undoubtedly play an increasingly important role, they may not represent the ideal solution for every building. In many applications, hybrid systems and alternative low carbon technologies may provide a more practical route to carbon reduction whilst balancing affordability, resilience and operational requirements.
UK governmental policy in financial assistance also further encourages heat pump ownership. The Boiler Upgrade Scheme provides £7,500 towards air or ground source heat pumps. The same scheme does not include hybrid systems and clearly favours heat pump technology.
Five years ago, the gap between policy and reality in terms of UK heat pump ownership was thoroughly discernible, now all trends appear positive and on an upwards trajectory.
Heat pumps are no longer an exotic "European" or "Scandinavian" technology, they are a viable and efficient form of heating and hot water provision. Significant work has been completed to make heat pumps market relevant and more affordable. There is a current harmony between policy and reality that is beginning to provide positive results and upwards momentum in all UK heat pump consumer trends. Heat pumps are an important part of the UK energy and appliance future.
The future is unlikely to be defined by a single technology. Instead, success will come from applying the right low carbon solution to the right building at the right time.
Rinnai will continue to locate and share any information and knowledge with all UK customers with the aim of assisting product or energy selection. Providing holistic commentary on any news pertaining to finance, technology and geopolitical events that influence energy costs or availability will assist potential customers in all decision-making processes.
Rinnai offers clear pathways to lower carbon and decarbonisation
Plus customer cost reductions for commercial, domestic
And off-grid heating & hot water delivery and off-grid heating & hot water delivery
-
Rinnai’s range of decarbonising products - H1/H2/H3 - consists of hot water heating units in gas/BioLPG/DME, hydrogen ready units, electric instantaneous hot water heaters, electric storage cylinders and buffer vessels, a comprehensive range of heat pumps, solar, hydrogen-ready or natural gas in any configuration of hybrid formats for either residential or commercial applications. Rinnai’s H1/2/3 range of products and systems offer contractors, consultants and end users a range of efficient, robust and affordable low carbon/decarbonising appliances which create practical, economic and technically feasible solutions.
-
Rinnai is a world leading manufacturer of hot water heaters and produces over two million units a year, operating on each of the five continents. The brand has gained an established reputation for producing products that offer high performance, cost efficiency and extended working lives.
-
Rinnai products are UKCA certified, A-rated water efficiency, accessed through multiple fuel options and are available for purchase 24/7, 365 days a year. Any unit can be delivered to any UK site within 24 hours.
-
Rinnai offer carbon and cost comparison services that will calculate financial, and carbon savings made when investing in a Rinnai system. Rinnai also provide a system design service that will suggest an appropriate system for the property in question.
-
Rinnai offer comprehensive training courses and technical support in all aspects of the water heating industry including detailed CPD’s.
-
The Rinnai range covers all forms of fuels and appliances currently available - electric, gas, hydrogen, BioLPG, DME solar thermal, low GWP heat pumps and electric water heaters More information can be found on Rinnai’s website and its “Help Me Choose” webpage.
Rinnai full product availability 24/7 for next day delivery of all hot water heating unit models including 48-58kW units.
Average savings of:
20% REDUCTION of Opex cost
30% REDUCTION of initial cost
15% REDUCTION in carbon
75% REDUCTION of space
For more information on the RINNAI product range visit our website.